

Current - Mobile Banking
by Current
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
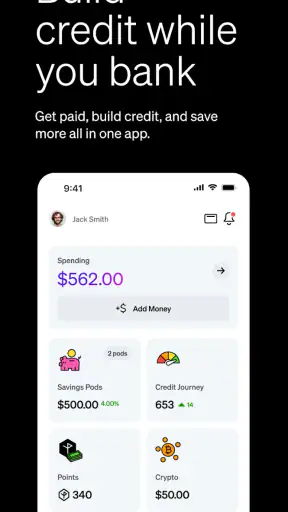
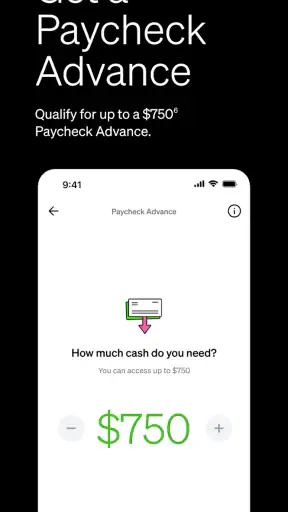
 Analysis by Getfullapps
Current is a finance app from Current that I would describe as a practical mobile banking companion rather than a complete replacement for every financial service. Its central appeal is straightforward: it brings everyday spending, early access to pay, and credit-building tools into one phone-based experience. I found the app easiest to appreciate when I treated it as a routine money-management tool instead of expecting it to solve every part of my finances.
The app is free, aimed at everyone, and works on Android devices running version 8.0 or later. It has been available since May 5, 2017, and the current release is version 8.13.0. Its store presence is substantial, with more than five million installs, a 4.4 average from roughly 179,000 ratings, and about 48,000 written reviews. Those figures suggest that Current has become a familiar option for people who want banking features designed around a smartphone.
How I use Current for an ordinary money routine
My preferred starting point is simple: I use the app to see what money is available, check recent activity, and separate immediate spending from money that needs to last. That basic workflow matters because a banking app can become stressful when it hides the information I need behind too many screens. Current generally makes the first check of the day feel direct, especially when I only want to confirm a balance or review a recent purchase.
A realistic example is getting paid before a busy week of travel, groceries, and bills. I would open Current, confirm the incoming money, review the balance, and decide how much is safe to spend before the next deposit. The early-pay angle can be useful in that situation, but I would still plan around my normal payday unless I had already confirmed how the feature applies to my own account. Access to money earlier is helpful only when it supports a stable budget rather than encouraging me to spend sooner.
The credit-building side also needs a deliberate routine. I would not treat it as a shortcut to a strong credit profile or as a reason to borrow more. Instead, I would use the app alongside regular payment habits, keep track of what is being used, and review the results over time. The most important practical lesson is that a credit feature is only helpful when it fits a wider plan for paying on time and keeping spending under control.
Current works best for people who want their daily financial decisions visible on a phone. It is especially approachable for someone who finds traditional banking websites cluttered or who wants one place to check spending between paydays. I also see value for users who are paid regularly but want earlier access when available, provided they understand the timing and conditions before relying on it.
It is less suitable for someone who needs a broad wealth-management platform, complex business banking, or detailed investment analysis. A person managing several accounts, complicated tax needs, or extensive savings goals may prefer a conventional bank combined with a dedicated budgeting or investment service. Current can be part of that setup, but I would not assume it replaces every specialist tool.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The first setup choices affect the whole experience
When I first approach a finance app, I avoid rushing through setup just to reach the home screen. I check how deposits, spending, and credit-related tools are presented, then make sure the account information is accurate. A few extra minutes here can prevent the common mistake of treating an available balance as the same thing as money that is genuinely free to spend.
I also recommend deciding in advance what the app is supposed to do for you. If the main goal is earlier access to pay, make that the center of the routine. If the goal is credit building, focus on consistent use and repayment behavior. If the goal is everyday spending control, review activity frequently. Trying to use every feature at once can make the app feel busier than it needs to be.
One useful habit is to review transactions at a fixed point in the day rather than opening the app repeatedly without a purpose. I prefer a quick check after a major purchase and a more complete review at the end of the day. This creates a repeatable pattern: confirm what changed, compare it with the plan, and adjust the next decision if necessary.
Settings and controls worth checking early
Experienced use of Current begins with the controls that affect how money moves and how the app communicates with me. I would inspect notification preferences first. Alerts can be valuable for keeping track of activity, but too many low-value notifications can make important messages easier to ignore. I prefer notifications that help me notice a meaningful change rather than constant reminders that add noise.
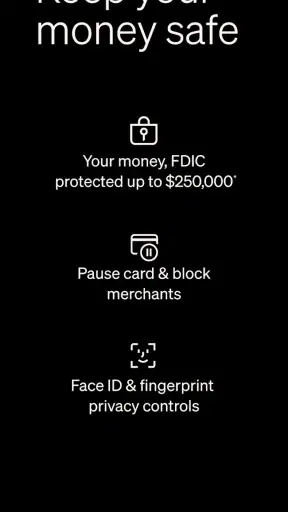
I would also review security and access options carefully. A finance app should be protected by the strongest practical device lock available, and I would avoid using it casually on a shared or unlocked phone. This is not a Current-specific trick; it is a necessary part of using any mobile banking service. The convenience of a banking app is only worthwhile when the phone itself is treated as part of the security boundary.
Another setting-related habit is checking the details around early pay before building bills around it. The phrase “get paid early” is attractive, but timing matters. I would confirm when funds are expected, what qualifies as an eligible deposit, and whether my employer’s payment process affects availability. If the money arrives later than expected, a budget based entirely on early access can create unnecessary pressure.
The same careful approach applies to credit-building tools. I would read the in-app explanations instead of assuming that the feature works like a conventional credit card or personal loan. The distinction matters because the spending process, repayment expectations, and effect on credit can differ from familiar products. Current is easier to use when I understand the role of each tool rather than judging everything by the standards of a traditional bank.
I would keep my profile and deposit details current as well. A mobile banking workflow depends on accurate personal information, and outdated details can turn a simple account task into a support issue. This is one of the less exciting parts of setup, but it is also one of the habits that separates dependable use from last-minute troubleshooting.
Faster patterns that make daily checks less tiring
The quickest way to use Current is to give each visit a purpose. For a balance check, I look only at the current position and recent changes. For spending control, I scan transactions and identify anything unfamiliar. For planning, I compare available money with upcoming needs. This sounds basic, but it prevents the app from becoming a place where I scroll without making a decision.
I like to group money decisions into repeatable moments. On payday, I check the deposit and decide what must remain untouched. After a large purchase, I review the new balance immediately. Before a weekend or trip, I make a short spending limit based on what is actually available. These patterns are more useful than opening the app whenever I feel anxious about money, because they turn checking into a controlled process.
A practical shortcut is to keep a small written note of upcoming commitments outside the app if Current is not your only financial service. I do not rely on one balance screen to remember every bill, subscription, or account. By comparing the Current balance with a separate list, I can distinguish money that is visible from money that is already mentally assigned. That reduces the risk of spending funds needed a few days later.
I would also avoid moving money around simply because the app makes the action convenient. Faster transfers can feel productive while actually making the budget harder to understand. My preference is to move money only when the purpose is clear, such as preparing for a known expense or correcting an intentional allocation. A clean routine is easier to audit than a series of small, unexplained changes.
For credit-building use, the faster pattern is not more activity; it is consistency. I would choose a manageable level of spending, monitor it, and make payments or follow the required process on schedule. The app may make the feature accessible, but the user still has to supply the discipline. That is an important trade-off: Current can simplify the workflow, but it cannot remove the consequences of careless money management.
Where the convenience reaches its limits
Current’s strongest features are aimed at everyday banking, and that focus is also its main boundary. I would not choose it as my only financial tool if I needed deep reporting, advanced account analysis, or a full view of complex household finances. People with multiple income sources or several financial goals may find that a dedicated budgeting system gives them more control than a single mobile banking app.
Early access to pay is useful, but it can change the psychology of a budget. Receiving money sooner may make a tight week easier, yet it can also make the next pay cycle feel shorter. I would use the feature as a timing convenience, not as evidence that I can afford a larger recurring expense. If a bill is only manageable because pay arrives early every time, the underlying budget probably needs attention.
Credit building has a similar limitation. It may be appealing to someone who wants a more guided way to work on credit habits, but it should not be confused with instant improvement. I would compare the app’s approach with the products already available to me and consider whether a secured card, traditional bank product, or nonprofit financial counselor would better match my situation. The better choice depends on the person’s existing credit history, spending control, and need for flexibility.
There is also a support trade-off with any phone-first service. I personally like the convenience of handling routine tasks from a mobile screen, but some users want a branch, a familiar local institution, or a more traditional customer-service relationship. If face-to-face help is important to you, Current may feel limited even when its app-based workflow is smooth.
Before making Current the center of a financial routine, I would test it with ordinary activity rather than immediately redirecting every deposit and payment. Use it for the tasks that matter most, observe how the timing fits real life, and make sure the account presentation is clear enough for your own budgeting style. This trial approach is especially sensible when early-pay timing or credit tools are the main reason for signing up.
Who should choose it, and who should look elsewhere?
I would recommend Current to someone who wants a straightforward mobile banking experience, values convenient access to pay when eligible, and is interested in a guided credit-building option. It is a good fit for users who prefer checking money from a phone and who are willing to create their own habits around balances, deposits, and spending.
I would be more cautious recommending it to someone who wants a single app for investing, detailed financial planning, business operations, and complicated account aggregation. A traditional bank may be better for branch access or extensive account services, while a dedicated budgeting app may provide more detailed category analysis. The choice is not about which product is universally best; it is about whether Current’s focused workflow matches the job you need done.
For families, I would think carefully about visibility and responsibility before using it as the main household account. A simple personal spending routine is easier to manage than shared finances with several people, irregular deposits, and many recurring obligations. Current can still be useful for an individual portion of that arrangement, but I would not assume that a personal mobile banking workflow automatically handles every family need.
My verdict after building a repeatable routine
Current succeeds when I use it with clear boundaries. I check deposits, review activity, understand what is available, and treat early pay as a convenience rather than extra income. I approach credit building patiently and keep the app connected to a wider plan instead of expecting it to repair financial habits on its own.
Its free price and Everyone rating make it approachable, while its large user base shows that the phone-first model appeals to many people. The developer, Current, has kept the product centered on accessible everyday finance rather than turning it into an overloaded financial dashboard. That focus is a strength for a user who wants fewer steps, but it is also why people with advanced needs may eventually add another service.
The best way to use Current is to combine its convenient features with deliberate habits. Check it at predictable times, adjust notifications so they remain useful, verify the rules around early pay, and never let a credit-building tool replace careful repayment behavior. With that mindset, it can be a helpful part of a personal money routine. Without it, the same convenience may encourage spending decisions made too quickly.
Overall, I would recommend giving Current a try if your priority is mobile banking with early-pay access and credit-building support. I would skip it as a sole financial hub if you need advanced planning, branch-based service, or extensive investment features. For the right user, it feels practical and easy to return to; for everyone else, a more traditional bank or a specialized budgeting tool may provide the depth that this focused app intentionally leaves out.
Pros
- User-friendly interface with intuitive navigation.
- Instant notifications for transactions and updates.
- Secure login with biometric authentication option.
- Comprehensive budgeting tools for financial tracking.
- Wide range of supported banking institutions.
Cons
- Limited offline functionality without internet access.
- Occasional delays in transaction updates.
- Some features require premium subscription.
- Customer support is not available 24/7.
- Frequent updates may require storage space.
FAQs for Current - Mobile Banking
What features does the Current mobile banking app offer?
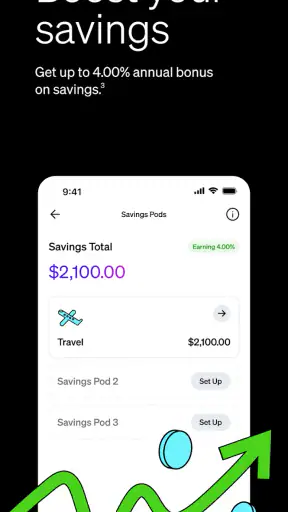
The Current mobile banking app offers a range of features including real-time spending notifications, budgeting tools, early direct deposits, and fee-free overdraft protection. Users can also enjoy perks like savings pods, instant money transfers, and a user-friendly interface designed to enhance financial management and convenience.
Is the Current app secure for managing my finances?
Yes, the Current app employs advanced security measures to protect your financial information. It uses encryption and secure servers to safeguard data. Additionally, features like biometric login and two-factor authentication enhance security, ensuring your money and personal details are well protected.
Are there any fees associated with using the Current app?
While many features of the Current app are free, certain services may incur fees. For instance, there might be charges for out-of-network ATM withdrawals. However, the app is transparent about any potential fees, providing users with detailed information to help manage their finances effectively.
Can I access customer support if I encounter issues with the app?
Yes, Current offers robust customer support to assist users with any issues. You can reach out through the app’s chat feature, email, or phone support. The support team is known for being responsive and helpful, ensuring users can resolve their queries efficiently.
Is the Current app compatible with both Android and iOS devices?
The Current mobile banking app is compatible with both Android and iOS devices. It is regularly updated to ensure smooth performance across different platforms, providing a seamless user experience whether you’re using a smartphone or tablet.

Current - Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@current.com, visit https://current.com, or review their https://www.current.com/privacy_policy.










